Want a 3-year plan? A 10-year plan? Right now you’re on the forever plan.
Take Steve and Amy, a family you’ll meet below. Their plan has them out of debt 21 years sooner than their payment schedule says, on the same paycheck. They didn’t earn more. They changed where it went. The credit cards and the cars are gone in under three years, the house follows, and they’ll save about $330,000 that would have gone to interest.
No gimmicks. No lectures. No system to buy. Your own money, sent to your own debt, on purpose.

We ran one family’s numbers through every payoff strategy that fit their situation, including the heavily marketed ones. The six best finished within about four months of each other. Strategy mattered far less than the money they freed and sent to the problem.
You don’t need a new personality or a complicated system. You need the money you already have, sent to the right debt, in the right order.
The lender didn’t cheat you. A loan schedule is arithmetic on a declining balance, and every number was disclosed before you signed. But disclosure isn’t comprehension.
You experience debt one month at a time, one payment at a time, and nobody ever adds it all up and shows you the lifetime number.
For a family carrying a mortgage, two car loans, and a few cards, that number runs into the hundreds of thousands of dollars in interest alone. It arrives quietly, and it does more than almost anything else to decide whether you reach 65 with assets or with payments.
What this is
Retire the right debt
DebtRetired is an advisory practice built around one idea: retire the right debt, so less of your money goes to lenders and more goes to your family’s net worth.
This is for families who have money left over each month and debt that’s quietly eating it.
Think about what retiring from work actually means. It doesn’t mean you never work again. It means any work you do from there on is by choice.
Debt retired means the same thing. The draining payments are gone, and any debt you keep, you keep on purpose, because it serves you.
For some families that means paying everything down to zero. For others it means keeping a low-rate mortgage on purpose and investing the money that frees up for your family’s future. That choice should come from your numbers, not from a rule of thumb.
We use professional planning software to model your payoff, and then we do the part software can’t do: judgment. The best instrument in the world doesn’t make music. Someone has to play it, and the real goal here is to walk with you until you’re comfortable playing it yourself.
Without refinancing. Without guesswork. And without a forever subscription, because you graduate.
How it works
1
See your date
Enter your balances, your rates, and what’s left over each month, and the planner shows how soon your debt could be done and how much interest you’d save. About three minutes.
If you’re guessing how much surplus money you have each month, and most people are, our free Cash Flow Calculator helps you figure it out so that earlier payoff date and the money you’ll save rest on something real.
2
Send it to the right debt, in the right order
Every payoff strategy ever sold comes down to four moves: pay more, pay sooner, pay less interest, owe less. The best plan is the mix of those four that fits your life.
3
Work the plan with an advisor
Get out of debt, stay out of debt, and graduate past it. Along the way you learn how debt really works, how lenders make their money, and how to play a different game. When your own habits are carrying the plan, you may not need an advisor or a mentor anymore. You decide that.
Ready to see how soon you could be out of debt and how much you can save? See your date →
Not sure about your monthly budget and expenses? Try the free calculator →
Meet Steve & Amy
Steve and Amy are a working couple in their fifties. Good income, a mortgage, two cars, some cards. Nothing about them is unusual, including this: on their current path, they’d be making payments until October 2053 and paying $404,010 in interest along the way.
Same income, replanned: consumer debt paid off in under three years, everything resolved by August 2032, and $5,052 a month that’s theirs again.
Steve and Amy are a composite household. Their numbers come from a real planning run, and the dates are the plan’s projection, not a report of results.
Who’s behind this
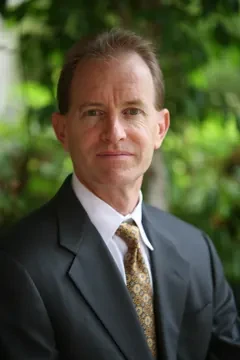
I’m Kent Kopen. I’ve spent 33 years in financial services helping families make important money decisions honestly and in plain language. This practice exists because the most neglected side of a household’s finances is the side quietly draining it: debt, also called liabilities.
See your date.
About three minutes in the planner, and you keep the result. Or talk it through with me first: 30 minutes on your real numbers.
Retire Debt • Build Wealth • Enjoy Life
Not ready yet? Get smarter first.
A newsletter to help you get out of debt quicker.
No spam. Unsubscribe anytime.